Electricity Industry Faces Risks from Three New Technologies
Saudi Aramco Looks to Raise $10 Billion from Real Estate Asset Deal Leonard S.
Hyman is an economist and financial analyst specializing in the energy sector.
He headed utility equity research at a major brokerage house and… Electric company annual reports describe technological risk in the vaguest of terms, asserting that firms face numerous, generalized risks— boiler plate to provide legal cover just in case something happens, such as an ET invasion.
What specific risks do the companies face? You’ll never know from reading their reports.
Anyway, it often takes years for something to happen in the utility industry, so why bother worrying now? Brokerage reports, generally optimistic, focus on a utility’s rate base growth (mostly their assets), AI demand, ongoing regulatory complacency all within a 3-5 year horizon.
Technological disruption of business that may be 5-10 years out seems beyond the decision time horizon of big investors.
They can always sell out ahead of time, right? “What, me worry?” sums up the picture, aided by lofty market valuations.
This relaxed attitude of utilities toward technology risk and their present business makes little sense for three reasons.
First, tech innovation can sneak up faster than expected, so the investor (the capital provider) might not have enough time to exit in an orderly fashion, and the company might not have enough time to prepare to deal with the financial disruption.
Second, a likely or probable event even five years in the future affects the value of utility capital investments made today that have expected 20-30 year lives.
Third, the utility industry overall pays so little attention to science and technology (it spends a pathetic 0.1% of revenues on R&D) that it may be the last to know when new technologies are about to emerge and disrupt their business.
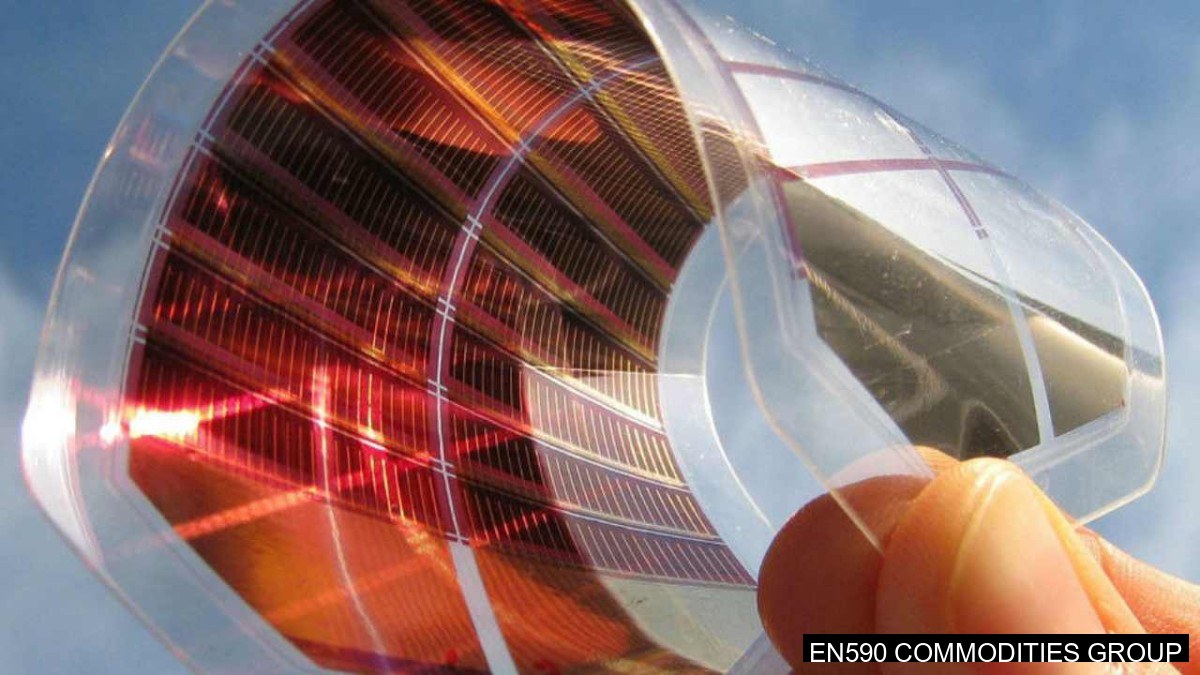
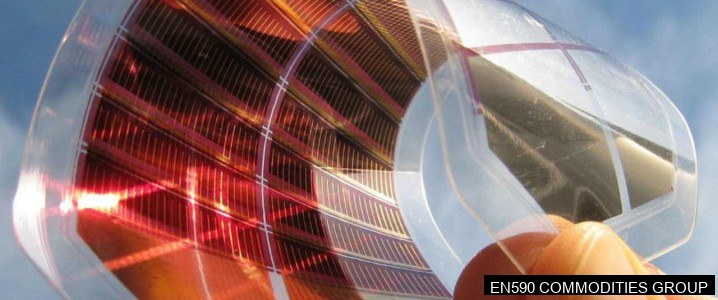
We could go into other reasons why the industry and its investors will tardily perceive or act on risks, including herd mentality, cultural issues, indexing, paradigm shifts, and regulation, but why bother? Simply put, we think that emerging technological developments, all staring us in the face right now, could start to disrupt the electricity industry’s structure and market in the coming 5-10 years.
| Product | Price | Change |
|---|---|---|
| Brent Crude | $102.14/bbl | ▲ +0.34% |
| WTI Crude | $96.90/bbl | ▲ +0.21% |
| EN590 Diesel | $846/MT | ▲ +0.18% |
| Jet Fuel A-1 | $1090/MT | ▲ +0.55% |
| Mazut M100 | $450/MT | ▼ -0.15% |
| Bitumen 60/70 | $470/MT | ▲ +0.08% |
| Sulphur Gran 99.5% | $470/MT | ▼ -0.44% |
| Urea 46% Gran | $650/MT | ▲ +1.12% |
| NPK 16-16-16 | $460/MT | ▼ -0.28% |
| Nat Gas TTF | $15.42/MMBtu | ▲ +0.92% |
Price alerts · Industry news
Comments
Post a Comment