Miller Value Deep Value Select Q3 2026 Commentary
saifulasmee chede/iStock via Getty Images saifulasmee chede/iStock via Getty Images During the third quarter, the equity market became even narrower as market participants reacted to greater uncertainty.
As we have seen over the past couple of years, rising Geopolitical and inflation concerns have led to increased market volatility.
The ongoing conflicts in Ukraine and the Iran War have put upward pressure on energy prices, while interest rates recently increased across government maturities.
With growing fears of stubborn inflation and higher interest rates, it’s not surprising that Mr.
Market recently favored larger market cap equities.
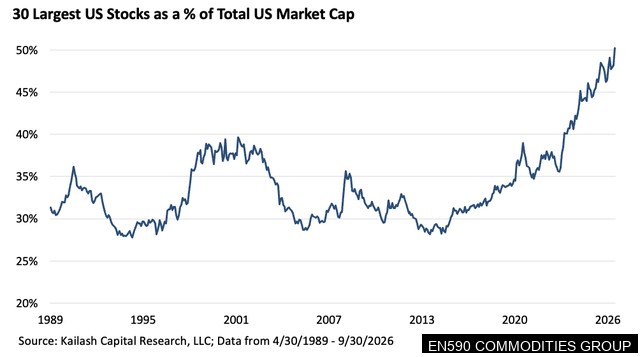
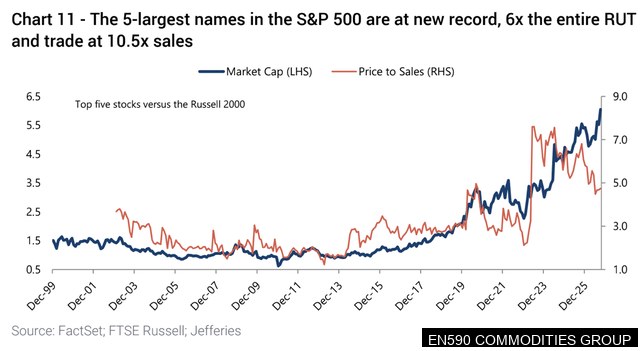
During the quarter, the 30 largest US Stocks as a percent of the Total US Market Capitalization climbed to a new record at 50%, which is one-third higher than the average between 1989 and 2022 and 1000bps above the 2000-01 dot.com peak! A closer look at the composition of the largest 30 stocks reveals ten of the top eleven are leading AI companies, whose weighting in the S&P 500 has doubled since 2023 to 41%, a level of concentration that was seen during prior market extremes (Nifty Fifty in the 1970s, Japan equities in the 1980s and TMT during the late 1990s).
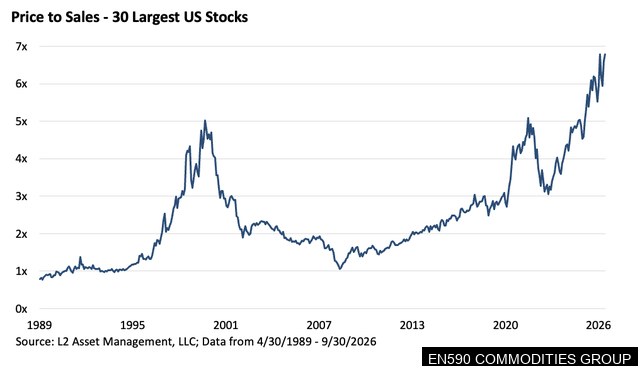
stocks price to sales multiple is now approaching 7x, nearly 40% higher than the 5x peak in 2000 and 2021! Here again, longer duration equities are fueling the valuation expansion as leading AI companies and technology stocks within the top 30 have an average price-to-sales over 15x.
High valuations embed in today’s prices lofty market expectations well into the future.
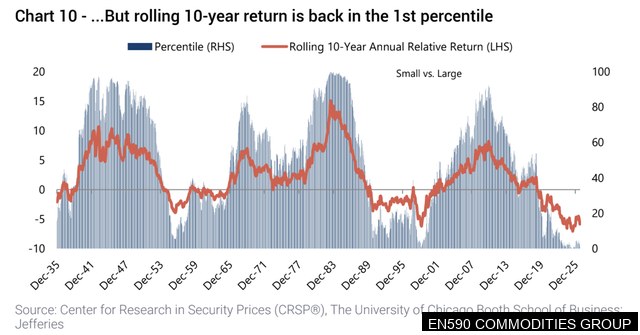
As a result, we believe the marketplace is overlooking the growing concentration risk of increasingly correlated large cap passive indexes.
An investor who believes they are diversified using passive indexes are becoming increasing vulnerable to an unexpected future correction in crowded longer duration equities.
For the past couple of years, there has been an ongoing positive feedback loop that supported the massive AI capex build-out.
AI-related companies have had an abundant amount of low-cost capital through ongoing Private Equity support, a favorable IPO market, circular financing relationships and debt markets that have demanded financing at a slight premium to the risk-free rate.
| Product | Price | Change |
|---|---|---|
| Brent Crude | $102.14/bbl | +0.34% |
| WTI Crude | $96.90/bbl | +0.21% |
| EN590 Diesel | $846/MT | +0.18% |
| Jet Fuel A-1 | $1090/MT | +0.55% |
| Mazut M100 | $450/MT | -0.15% |
| Bitumen 60/70 | $470/MT | +0.08% |
| Sulphur Gran 99.5% | $470/MT | -0.44% |
| Urea 46% Gran | $650/MT | +1.12% |
| NPK 16-16-16 | $460/MT | -0.28% |
| Nat Gas TTF | $15.42/MMBtu | +0.92% |
Comments
Post a Comment